
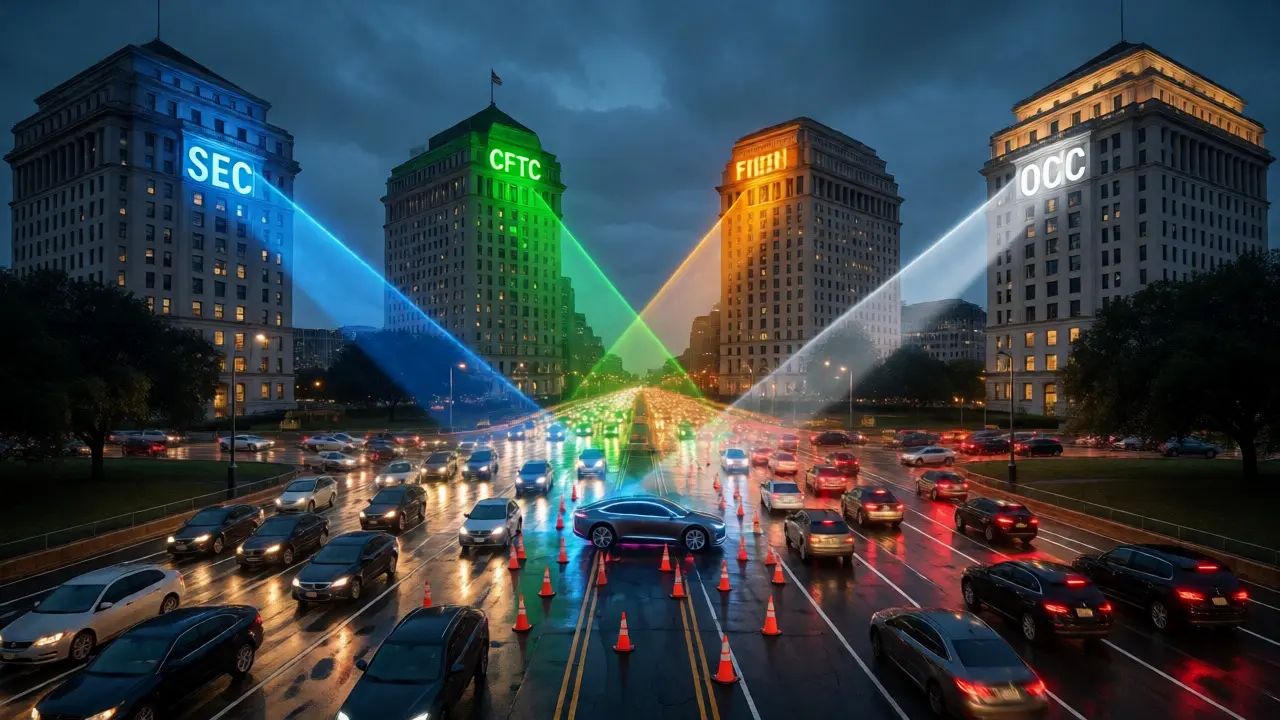
Imagine trying to drive a car where the traffic lights are controlled by four different agencies that don't always talk to each other. That is essentially what it feels like to run a cryptocurrency business in the United States right now. You have the SEC looking at your token as a security, the CFTC treating it as a commodity, FinCEN tracking every dollar for money laundering, and the OCC watching over the banks that touch your funds.
This isn't just bureaucratic noise; it's a multi-trillion-dollar reality. With the US crypto market valued at $1.2 trillion in 2025 and 45 million active users, getting this wrong can cost you millions in fines or worse, shut down your operations. The good news? The fog is lifting slightly. New guidance from late 2025 and the pending CLARITY Act are starting to draw lines in the sand. But until those laws pass fully, you need to know exactly which regulator owns which part of your business.
The Big Four: Who Does What?
Let's break down the roles without the legal jargon. Think of these agencies as having specific lanes on a highway. If you cross into someone else's lane, you get pulled over.
The Securities and Exchange Commission (SEC) is the strict parent figure here. They care about investor protection. Their main tool is the Howey Test, which asks: Did people invest money in a common enterprise expecting profits primarily from the efforts of others? If yes, your token might be a security. This means you need registration, disclosure, and heavy compliance. In 2023, a major ruling against Ripple Labs showed that not all sales are securities-specifically, sales to retail buyers on exchanges were deemed non-securities. This nuance matters. The SEC’s recent focus has shifted toward defining jurisdiction clearly, with Commissioner Hester Peirce leading a new Crypto Task Force to map out how broker-dealers and custody services fit in.
The Commodity Futures Trading Commission (CFTC) takes the opposite view for most major coins. Bitcoin and Ethereum are officially commodities under their watch. They regulate derivatives, futures, and spot markets if they deem the asset a commodity. The CFTC doesn't care about your whitepaper promises to investors; they care about fraud, manipulation, and whether your exchange plays fair. Remember the $100 million fine against BitMEX in 2020? That was the CFTC cracking down on lax anti-money laundering controls and unregistered trading platforms.
FinCEN (Financial Crimes Enforcement Network) is everywhere. Unlike the SEC or CFTC, FinCEN doesn't classify tokens as securities or commodities. Instead, they apply the Bank Secrecy Act to everyone handling virtual currency. If you transmit value, you are likely a Money Services Business (MSB). This triggers Anti-Money Laundering (AML) and Counter-Terrorism Financing (CFT) requirements. You must file reports, keep records, and verify identities. In 2023, FinCEN proposed stricter rules for mixing services like Tornado Cash because criminals use them to hide illicit funds. If you ignore FinCEN, you aren't just facing civil penalties; you're risking criminal liability.
The Office of the Comptroller of the Currency (OCC) is the gatekeeper for banks. They don't regulate crypto directly unless a national bank gets involved. Since 2020, the OCC has allowed national banks to offer crypto custody and hold stablecoin reserves. As of December 2025, 47 national banks offer these services. If you want traditional banking rails for your crypto business, you need the OCC to bless your partner bank. They require banks to notify supervisors before engaging in any crypto activity, creating a de facto approval process for institutional adoption.
Jurisdictional Conflicts and the CLARITY Act
Here is the problem: The same token can be a security to one agency and a commodity to another. Or neither. Payment stablecoins, for example, currently sit in a regulatory gray area. They aren't quite securities, and the CFTC hasn't fully claimed them as commodities for market regulation purposes. This gap leaves room for arbitrage but also creates massive uncertainty.
Enter the CLARITY Act, introduced in May 2025. This legislation aims to fix the overlap. It proposes giving the CFTC exclusive jurisdiction over digital commodity spot markets while letting platforms choose between SEC or CFTC registration based on what they trade. However, critics note it still leaves payment stablecoins outside clear market surveillance frameworks. Professor Hilary Allen from American University testified in early 2025 that current rules create perverse incentives, pushing projects to avoid decentralization just to stay under one regulator's thumb.
A recent Harmonization Statement from September 2025 between SEC Chair Paul Atkins and CFTC Acting Chair Caroline D. Pham signals a truce. They committed to aligning their frameworks, aiming to provide "markets the clarity they deserve." While this is promising, it is not law yet. Until Congress passes the CLARITY Act, you are navigating a patchwork.
| Agency | Primary Focus | Key Legal Framework | Who Regulates? |
|---|---|---|---|
| SEC | Investor Protection, Fraud | Securities Act, Howey Test | Tokens deemed "Securities" |
| CFTC | Market Integrity, Derivatives | Commodity Exchange Act | Tokens deemed "Commodities" (e.g., BTC, ETH) |
| FinCEN | AML/CFT Compliance | Bank Secrecy Act | All Virtual Asset Service Providers (VASPs) |
| OCC | Bank Safety & Soundness | National Banking Acts | National Banks offering crypto services |
Compliance Costs and Real-World Impact
You might think, "I'm small, do I really need to worry?" Yes. A 2025 survey by the Chamber of Digital Commerce found that 78% of crypto firms spend over $1 million annually on regulatory compliance. Forty-three percent cited conflicting agency requirements as their biggest headache. It’s not just big players like Coinbase or Binance feeling the heat. Small startups are relocating. Sixty-two percent of US crypto startups considered moving operations abroad due to this uncertainty, up from 48% in 2022.
Why so expensive? Because you often have to satisfy multiple masters. If you launch a token sale, the SEC wants disclosures. If you list it on an exchange, the CFTC wants surveillance data. And no matter what, FinCEN wants your KYC (Know Your Customer) records tight. Missing one piece can trigger parallel actions. As noted in a 2019 joint statement analysis, regulators may bring cases simultaneously if jurisdictions overlap, forcing you to defend yourself on two fronts at once.
Stablecoins and DeFi: The Emerging Battlegrounds
Stablecoins are the next flashpoint. The OCC allows banks to hold reserves, but who regulates the issuer? Currently, it’s messy. Some states issue money transmitter licenses, but federal oversight is fragmented. FinCEN treats stablecoin issuers as MSBs, requiring AML checks. But market conduct rules? Those are unclear.
Decentralized Finance (DeFi) poses an even bigger challenge. Who is responsible when a protocol has no central entity? FinCEN has started addressing this by targeting mixers and proposing rules for decentralized exchanges. The idea is that even if code governs the transaction, someone must be accountable for anti-money laundering. If you build a DeFi app, assume you will eventually need a compliance layer, even if you claim to be "trustless."
Practical Steps for Navigating the Maze
So, how do you survive? First, classify your asset honestly. Run it through the Howey Test mentally. Is there a central team driving profits? Likely a security. Is it purely functional and decentralized? Maybe a commodity. Don't guess; consult counsel.
Second, prioritize FinCEN compliance. Regardless of token classification, if you move money, you need an AML program. Implement robust KYC procedures immediately. Use blockchain analytics tools to screen transactions against OFAC sanctions lists. Sanctioned entities like Blender.io prove that ignoring sanctions risks freezing your funds.
Third, engage with the OCC indirectly. If you need banking partners, ensure they understand their reporting obligations to the OCC. Choose banks that have explicitly notified their supervisors about crypto activities. This reduces the risk of sudden account closures.
Finally, monitor the CLARITY Act. If it passes, expect shifts in registration duties. Keep an eye on the SEC-CFTC harmonization efforts. Joint roundtables suggest future rules may align more closely, reducing dual-regulation burdens.
Is Bitcoin regulated by the SEC or CFTC?
Bitcoin is primarily regulated by the CFTC as a commodity. The SEC generally agrees that Bitcoin is sufficiently decentralized to not be a security. However, both agencies retain authority over fraud and manipulation cases involving Bitcoin.
What happens if my token is classified as a security?
If your token is a security, you must comply with SEC regulations, including registration or exemption filings, regular disclosures, and antifraud provisions. Failure to do so can result in enforcement actions, fines, and forced refunds to investors.
Does FinCEN regulate all cryptocurrencies?
Yes, FinCEN applies Anti-Money Laundering (AML) rules to all virtual currencies used in financial transactions. Any business transmitting value must register as a Money Services Business (MSB) and implement AML programs, regardless of whether the asset is a security or commodity.
Can banks hold crypto for customers?
Yes, national banks can offer crypto custody services under OCC guidance issued since 2020. These banks must maintain adequate reserves and follow strict safety and soundness standards. Over 47 national banks offered these services as of late 2025.
What is the CLARITY Act?
The CLARITY Act is proposed legislation designed to clarify jurisdictional boundaries between the SEC and CFTC. It would grant the CFTC primary oversight of digital commodity spot markets while preserving SEC authority over securities, aiming to reduce regulatory overlap and uncertainty.