
Imagine you are a small supplier waiting three months to get paid by a massive retailer. You need cash now to buy raw materials, but banks won't lend to you because they don't trust your paperwork or your credit history. The retailer is trustworthy, but that trust doesn't transfer to the bank easily. This is the classic supply chain bottleneck. Now, imagine if that retailer's promise to pay could be split into digital tokens, verified instantly on a shared ledger, and sold to an investor in seconds. That is Supply Chain Financing a set of solutions used by buyers and suppliers to optimize working capital, enhanced here by distributed ledger technology.
Blockchain isn't just about cryptocurrency speculation. In the context of B2B transactions, it solves a specific problem: how to create a single source of truth for invoices and payments across multiple parties who don't fully trust each other. If you are trying to understand whether this tech actually helps businesses get paid faster or if it is just buzzword soup, we need to look at how the workflow changes, where it fails, and what the real numbers say.
The Core Problem With Traditional Invoice Financing
In traditional invoice factoring or discounting, a supplier sells their unpaid invoice to a financier (like a bank) at a discount. The financier advances most of the cash immediately. When the buyer pays the due date, the money goes to the financier. Sounds simple, right? But the friction is high. Banks have to verify that the invoice is real, that the goods were delivered, and that the invoice hasn't been sold twice. They do this via emails, PDFs, phone calls, and manual checks. This process takes days or weeks. It is expensive, prone to fraud, and often excludes smaller suppliers who lack the resources to manage complex documentation.
Smart Contracts self-executing contracts with the terms of the agreement directly written into code attempt to automate these checks. Instead of a human verifying that a delivery receipt matches an invoice, a smart contract can check if a digital signature from the buyer’s warehouse system confirms the delivery. If the conditions match, the payment logic triggers automatically. This reduces the time between invoice creation and funding from weeks to hours, sometimes even minutes.
How the Workflow Actually Works
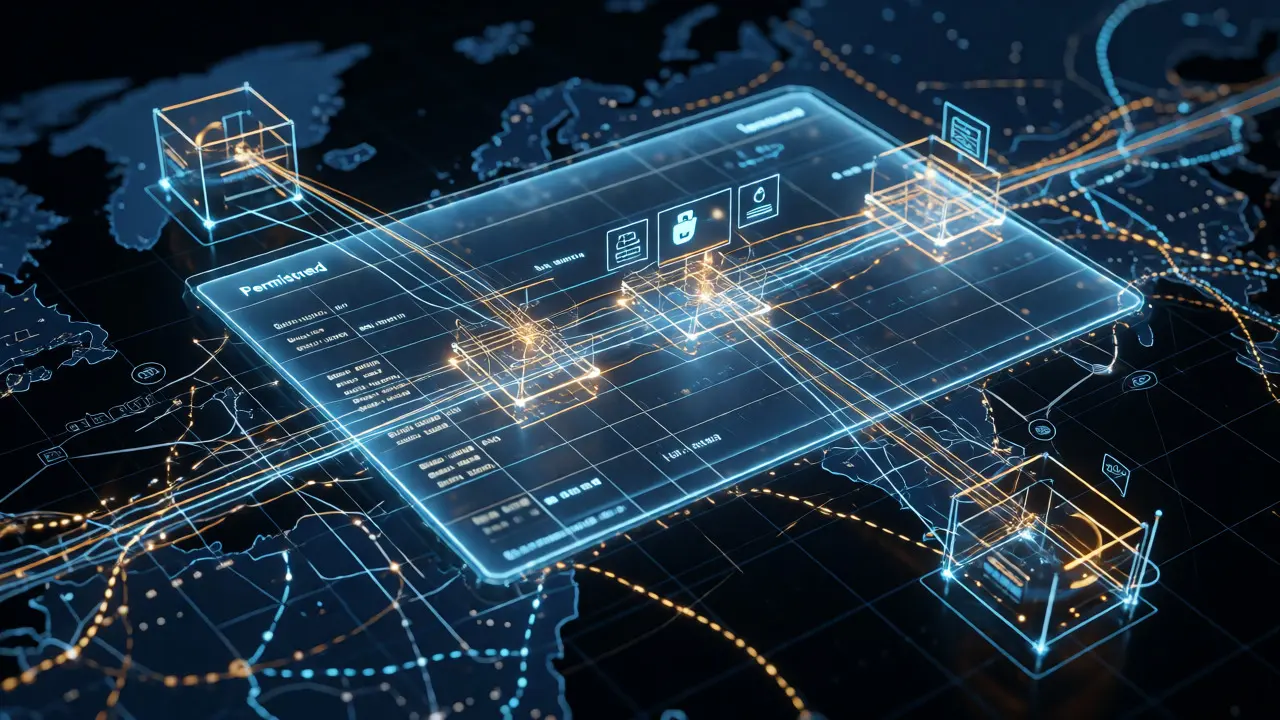
Let’s walk through a typical blockchain-enabled transaction. It starts when a buyer issues a purchase order. The supplier delivers the goods. Then, instead of emailing a PDF invoice, the supplier submits a digital invoice record to a permissioned blockchain network. This record includes the amount, currency, tax details, and a cryptographic hash linking it to the original purchase order and delivery confirmation.
The buyer logs in and approves the invoice. This approval is recorded on the ledger as an immutable event. At this point, the invoice becomes a verifiable asset. Because the ledger is shared among the buyer, supplier, and potentially several financiers, everyone sees the same status. No one can secretly change the amount or claim they haven't received the goods if the data says otherwise.
Once approved, the supplier can choose to sell this receivable. On platforms like those developed by Ant Group a Chinese multinational technology company focused on digital payments and financial services, this receivable might be tokenized. Tokenization means splitting the value of the invoice into smaller digital units. A large corporate buyer’s credit rating backs these tokens, making them attractive to investors who might not normally lend to small suppliers. The financier buys the tokens, funds are released to the supplier, and the smart contract handles the settlement when the buyer eventually pays.
Architecture: Permissioned vs. Public Ledgers
You might wonder why companies don’t use Bitcoin or Ethereum for this. The answer is privacy and speed. Most enterprise supply chain networks use Permissioned Blockchains distributed ledgers where access rights are restricted to a group of participants. Platforms like R3 Corda or Hyperledger Fabric allow only known, verified entities to join the network. This is crucial because trade secrets matter. You don’t want your competitor seeing your pricing strategy or volume discounts on a public blockchain.
| Feature | Public Blockchain | Permissioned Blockchain | Centralized Database |
|---|---|---|---|
| Privacy | Low (transparent) | High (selective disclosure) | High (internal control) |
| Trust Model | Code-based trust | Consortium governance | Institutional trust |
| Speed/Cost | Variable fees, slower | Fast, low cost per tx | Fastest, lowest cost |
| Auditability | Immutable public audit | Shared audit trail | Single-point audit risk |
Permissioned chains offer a middle ground. They provide the immutability and shared view of a blockchain without exposing sensitive commercial data to the world. However, they require strong governance. Who decides which nodes stay in the network? What happens if a major participant leaves? These are political and legal questions, not just technical ones.
Real-World Results and Failures
It is easy to get excited about the potential, but let’s look at what has actually happened. HSBC and ING conducted a pilot with Cargill using R3 Corda. They reported reducing document checking and exchange times from five to ten days down to less than 24 hours. Similarly, the platform we.trade managed to complete certain trade finance transactions in under a day compared to the traditional 10-12 days for letters of credit.
However, success stories are often cherry-picked. Consider TradeLens, a massive project backed by IBM and Maersk. It aimed to digitize global shipping documents. Despite having over 1,000 participants and tracking millions of containers, it shut down in 2023. Why? Not because the technology failed, but because the business model did not work. Competitors were hesitant to share data on a platform seen as controlled by their rivals. Integration costs were high, and many users didn’t see enough immediate value to justify the switch.
This highlights a critical lesson: blockchain is not a magic wand. If the underlying process is broken, automating it with blockchain just gives you a faster broken process. The technology works best when there is a genuine need for multi-party trust and when all stakeholders agree on standards. Without that alignment, even the best code cannot force adoption.
Benefits for Small and Medium Enterprises (SMEs)
For big corporations, blockchain SCF is about efficiency. For SMEs, it is about survival. According to the World Economic Forum, the global trade finance gap-the difference between demand and supply of trade finance-was estimated at $1.5 trillion in 2017. Blockchain has the potential to bridge part of this gap by lowering the cost of verification.
When a large, creditworthy buyer approves an invoice on the blockchain, that approval carries weight. Financiers can rely on the buyer’s credit rather than the SME’s balance sheet. This allows smaller suppliers to access cheaper capital. Ant Group reported that a merchant with minimal registered capital obtained a loan in one second against supply-chain commitments. While this is a vendor-reported figure, it illustrates the theoretical capability of extending credit visibility down the supply chain tiers.
Risks and Implementation Challenges
Don’t ignore the risks. A 2024 threat analysis identified over 40 distinct security threats in blockchain-based invoice factoring. These include stolen private keys, oracle manipulation (where fake external data is fed into the smart contract), and collusion among members. If a dishonest participant uploads a fraudulent delivery confirmation, the blockchain will immutably record that lie. Garbage in, garbage out still applies.
Legal frameworks are also catching up slowly. Laws regarding electronic transferable records vary by country. UNCITRAL’s Model Law provides a template, but local implementation matters. Can a digital token on a blockchain legally represent ownership of a physical good? In some jurisdictions, yes; in others, no. Cross-border transactions add another layer of complexity due to differing regulations on data privacy (like GDPR in Europe) and financial compliance.
Is It Worth It?
If you are a single company controlling your own database, you probably don’t need blockchain. A centralized SQL database is faster and cheaper. Blockchain adds value when you have multiple independent organizations that need to share a record but don’t fully trust each other. It shines in high-value, multi-tier supply chains where visibility and fraud prevention are worth the integration cost.
The future likely holds a hybrid model. We won’t see every invoice on a public chain. Instead, expect standardized APIs connecting ERP systems, bank rails, and selective blockchain layers for critical provenance and payment automation. The goal isn’t to replace banks or lawyers, but to give them better tools to make decisions faster.
Does blockchain eliminate the need for banks in supply chain finance?
No. Blockchain improves transparency and speed, but banks still provide the actual capital, regulatory compliance, and risk assessment. Smart contracts automate the execution of agreements, but they do not replace the financial institution backing the loan.
Can any invoice be financed using blockchain?
Not necessarily. The invoice must be digitally native or easily digitizable, and the buyer must be willing to participate in the network. High-friction industries with poor digital infrastructure may find the integration costs outweigh the benefits initially.
What is the main reason blockchain supply chain projects fail?
Lack of network effect and unclear economic incentives. Projects like TradeLens failed not because the tech didn't work, but because competitors didn't want to share data, and smaller players couldn't afford the integration, leading to insufficient participation.
Are smart contracts legally binding?
This depends on jurisdiction. Many regions are updating laws to recognize electronic signatures and smart contracts. However, disputes often still require traditional legal interpretation, especially if the code contains bugs or ambiguous terms.
How does blockchain reduce fraud in invoicing?
It creates an immutable audit trail. Once an invoice is hashed and recorded, it cannot be altered without detection. This prevents double-financing (selling the same invoice twice) and ensures that the document presented to the financier matches the one agreed upon by the buyer and seller.